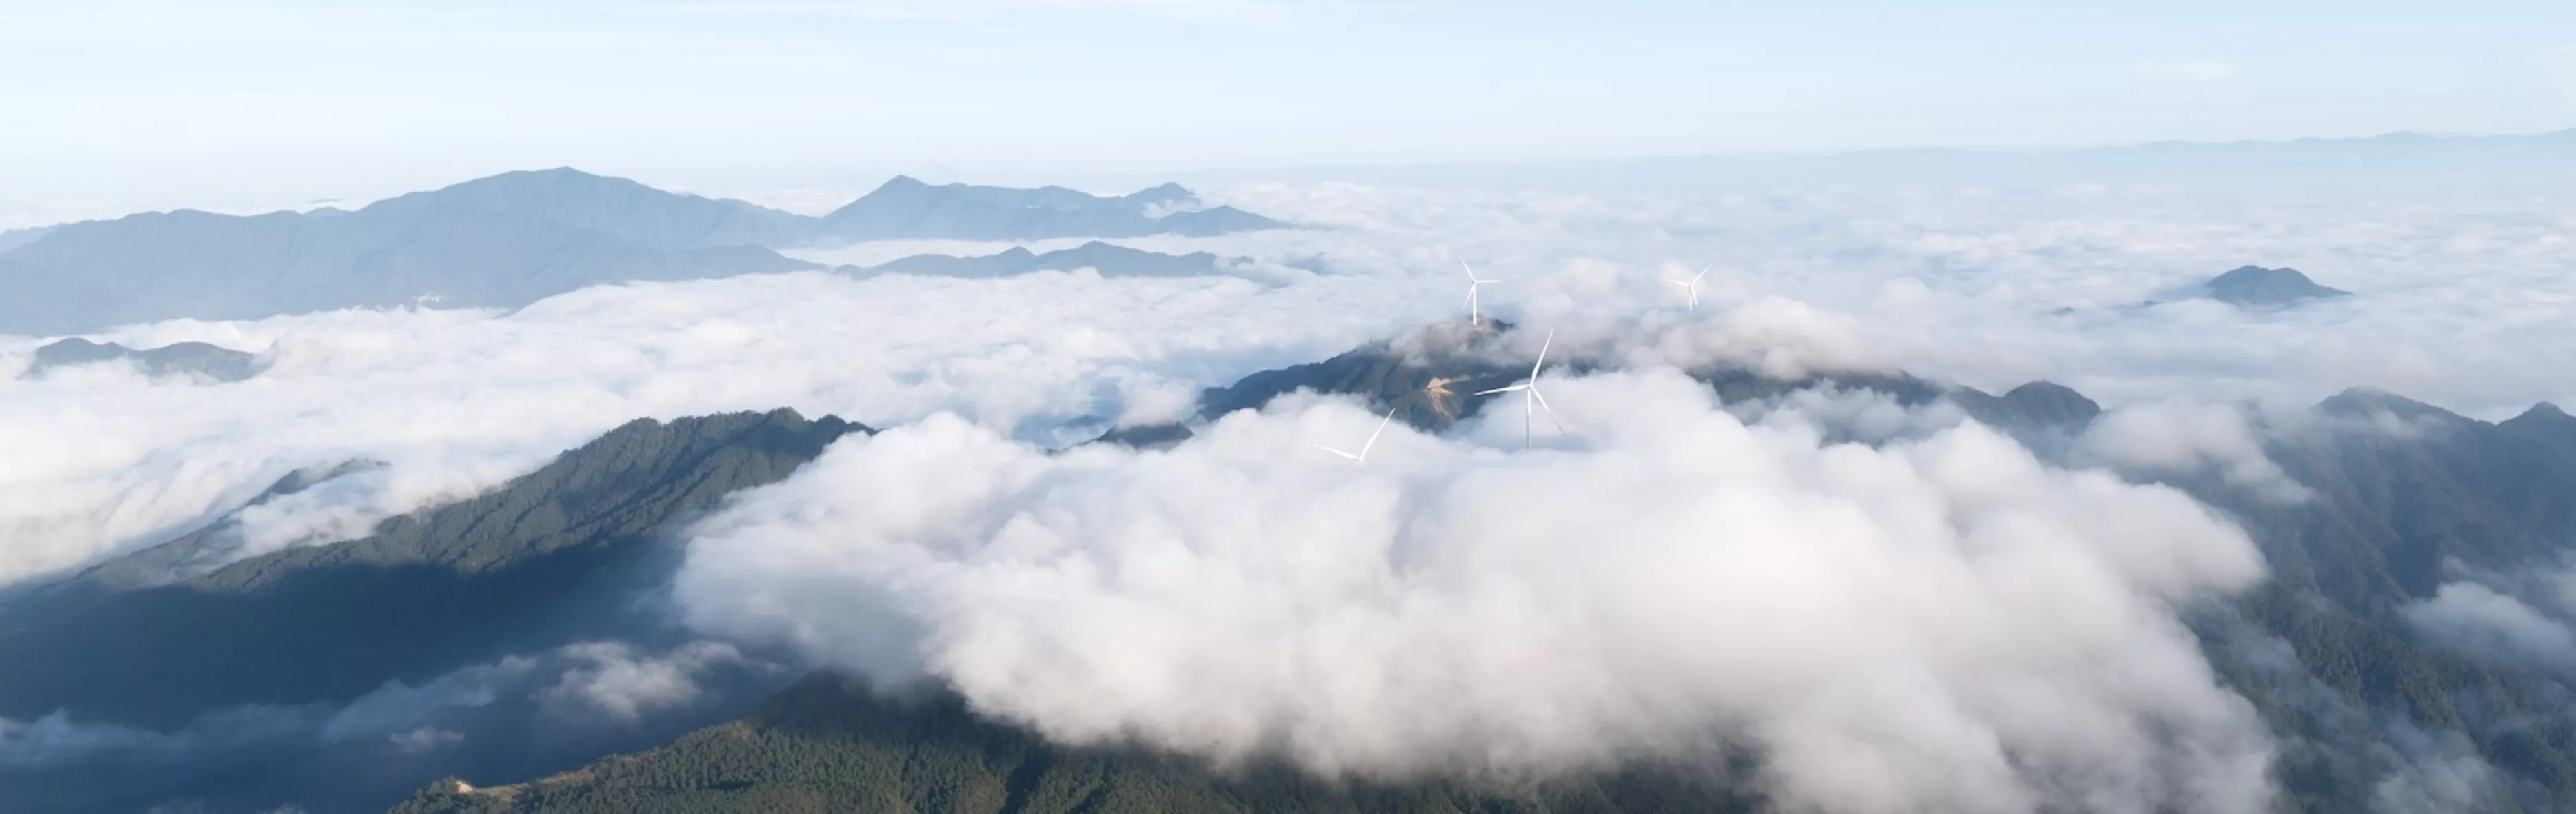
Copenhagen Infrastructure Partners (CIP), the Danish infrastructure investment giant, recently announced it has acquired the Gawara Baya wind-storage project in northern Queensland from Australian renewable energy developer Windlab via its fifth flagship fund. The company has simultaneously taken the final investment decision (FID) and completed financial close on the project.
The project comprises 408 MW of onshore wind paired with 104 MW of battery energy storage, featuring 68 turbines. It has secured a A$1.7 billion loan facility from a consortium of 10 banks, locked in a long-term power purchase agreement (PPA), and been accepted into Australia’s Capacity Investment Scheme. Full commercial operation is scheduled for 2030.
What has really caught the industry’s eye, however, is the follow-up report from Finans: CIP has officially confirmed in writing that the project will use wind turbines manufactured by Goldwind, China’s largest wind turbine OEM.
Why does this matter?
Breaking down the key details: the buyer is a top-tier European energy fund with around €43 billion in assets under management, the project is based in Australia, and the turbine supplier is Goldwind, China’s leading wind turbine manufacturer.
A top European fund selecting Chinese turbines for an Australian project is in itself a telling market signal. In third markets outside Europe, European developers’ adoption of Chinese turbines is no longer a series of isolated cases – it is hardening into a sustained trend.
Not an isolated case: 4.4 GW and counting
Gawara Baya is far from the first example. According to BloombergNEF, European wind developers have deployed Chinese turbines in projects totalling 4.4 GW across 23 countries and regions outside Europe since 2020. French energy majors Engie, EDF and TotalEnergies have been the leading buyers, with Chile, Kazakhstan and Türkiye emerging as the key markets.
There is already a long list of precedents: ENGIE sourced Goldwind turbines for its Pemuco and Chequenes wind farms in Chile, while EDF selected Goldwind for its 420 MW Koruson 1 wind cluster in South Africa. CIP’s Gawara Baya project marks the latest milestone as this trend extends to the Australian market.
Commercial logic: price differential drives decisions
From a project return perspective, the European developer’s choice is far from surprising.
Wood Mackenzie data shows that Chinese turbines are priced 19–24% lower than Western models in overseas markets – roughly 20% cheaper in Europe and around 22% cheaper in Asia-Pacific. A more stark comparison comes from Vestas: its average order backlog price stood at around RMB 8,790 per kW at the end of 2025, while the average winning bid for domestic offshore turbines in China was just RMB 3,200–3,600 per kW over the same period. Even after factoring in export premiums, Chinese turbines still carry a price discount of over 20% compared to European OEMs.
The budget for one European-built turbine can buy nearly two Chinese equivalents. For any infrastructure fund targeting stable returns, a price gap of this magnitude represents an unignorable cost advantage.
Delivery capability: Europe’s supply chain bottleneck
Beyond price, delivery is another critical factor.
In 2026, offshore wind capacity up for auction in Europe is set to exceed 20 GW, an all-time high. Yet domestic turbine supply is extremely tight. Output from manufacturers including Vestas and Siemens Gamesa falls far short of demand, with some players’ production schedules booked out to 2030.
Over recent years, European domestic OEMs have been hit by successive supply chain disruptions and quality issues, leading to lengthened lead times and sustained price increases. Chinese wind power companies, by contrast, control over two-thirds of global turbine manufacturing capacity and more than 70% of global key component output, making them the only supplier that can simultaneously deliver scale, cost competitiveness and reliable lead times.
CIP’s calculus: European capital, Chinese turbines, Australian market
Looking at Gawara Baya itself, CIP’s choice of Goldwind is essentially a classic formula of “European capital + Chinese turbines + Australian market”. CIP’s European institutional capital targets stable returns; Goldwind’s turbines are over 20% cheaper than European brands; and Australia offers a mature electricity pricing mechanism with long-term revenue security underpinned by the government’s Capacity Investment Scheme.
With a locked-in long-term PPA, government subsidies in place, and A$1.7 billion in bank financing from 10 lenders secured, the project’s cash flows are highly predictable. Against this backdrop of certainty, selecting the most cost-competitive turbines is a rational choice driven by fiduciary duty.
Gawara Baya holds up a mirror to the true landscape of the global wind industry: European developers are voting with their capital for Chinese turbines in markets from Chile and Kazakhstan to Türkiye and Australia, while Chinese OEMs continue to expand their footprint in third markets on the back of their three-pronged advantage in cost, capacity and delivery.
As long as Chinese turbines maintain their significant price advantage, world-leading manufacturing share and shorter lead times compared to European peers, European developers will continue to treat Chinese turbines as a key option for their projects outside Europe.