As one of the world's top ten wind turbine manufacturers, GE Vernova delivered a dismal performance report for 2025.
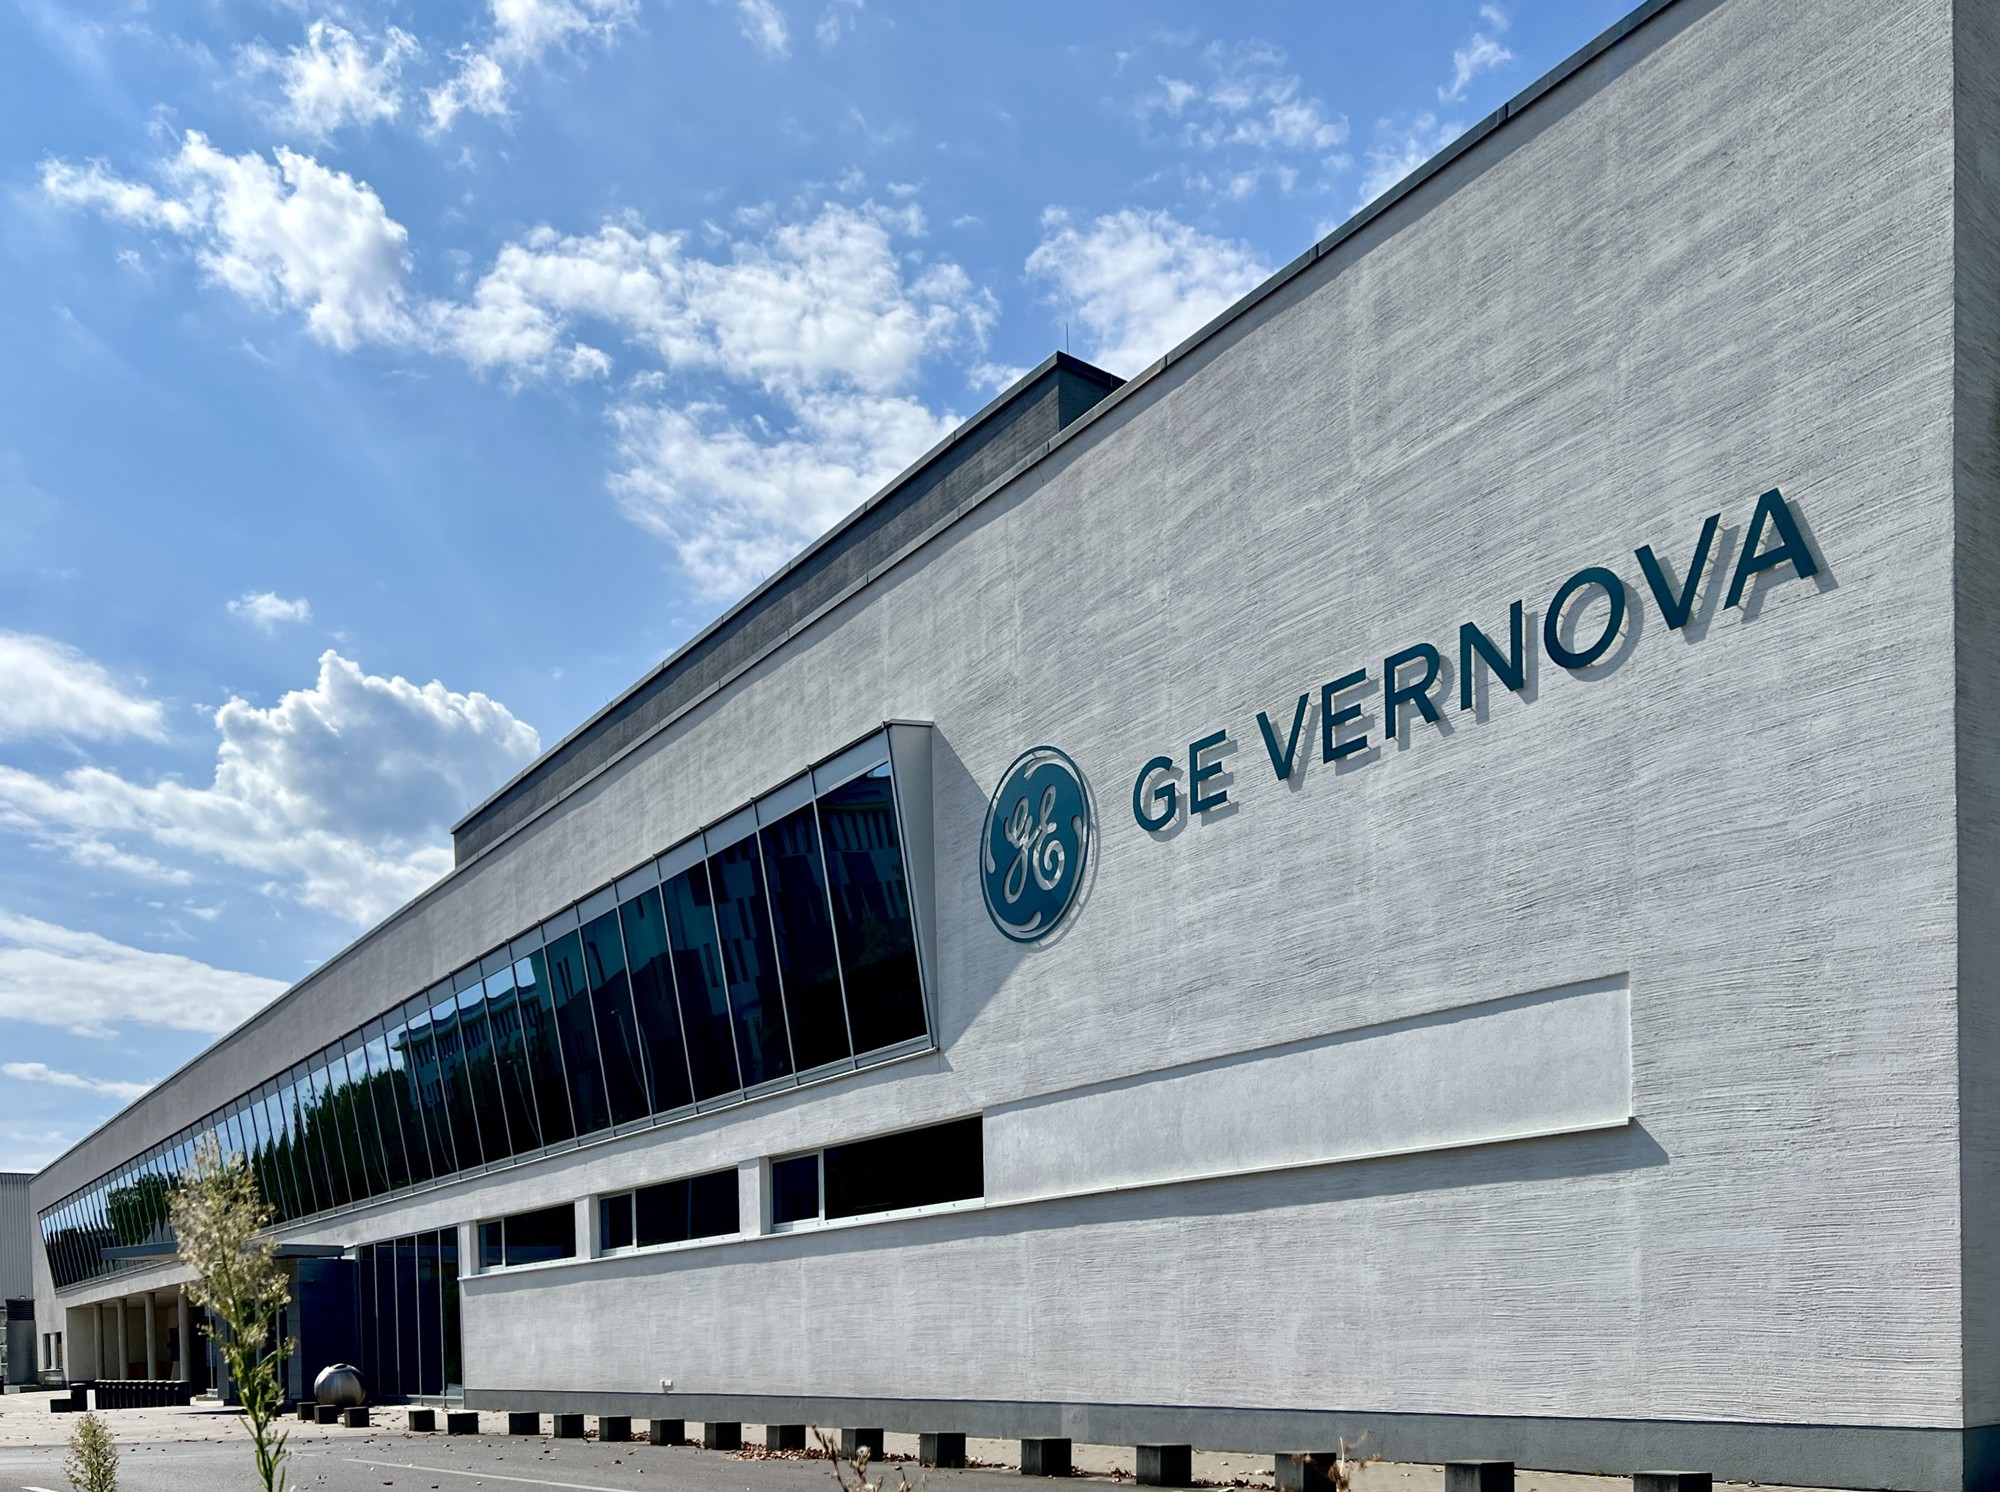
According to GE Vernova's latest report, the company's wind power business recorded an EBITDA loss of $598 million for the full year. This figure not only represents a further increase from the $588 million loss in 2024 but also significantly exceeds the market's previous expectation of a $400 million loss target.
Amidst performance pressures, multiple adverse factors converged to drive revenue decline. Affected by reduced equipment shipments, stalled offshore wind projects, and external shocks from international trade tariffs, GE Vernova's 2025 wind power business revenue fell 6% year-on-year, with total revenue shrinking to $9.1 billion.
Despite challenging operating conditions, GE Vernova's wind power order business achieved breakthrough growth against the trend. Benefiting from the steady recovery in global onshore wind power market demand, the company secured wind power orders totaling $7.7 billion in 2025, representing an 8% organic year-over-year increase. Concurrently, it successfully secured a 1,100 MW onshore wind power retrofit order in the U.S. market.
In stark contrast to GE Vernova's persistent losses, Siemens Gamesa demonstrated positive transformation results in the 2024-2025 fiscal year. Financial reports indicate that Siemens Gamesa recorded a loss of €1.36 billion for the fiscal year, representing a significant reduction of €420 million—or 23.6%—from the previous year's €1.78 billion loss. Concurrently, the company achieved a 3.7% revenue growth against market headwinds, with total revenue climbing to €10.3 billion. This demonstrates the business resilience of the enterprise amid deep restructuring efforts.
Against the backdrop of overall pressure in the global wind power industry, Nordex Group emerged as a standout “dark horse” in the 2025 turbine market. As one of the world's top ten wind turbine manufacturers, its 2025 performance report reveals that the company's new orders excluding service business reached 10,214 MW, surging 22.5% year-on-year from 8,336 MW in 2024, demonstrating exceptionally robust order growth momentum. Meanwhile, its average annual sales price for turbines remained stable at 0.91 million euros per MW, maintaining consistent pricing levels despite the industry-wide pressure of high costs.
Compared to the significant performance fluctuations seen in other companies, Vestas has consistently maintained a steady growth trajectory. According to its 2025 financial outlook report, the company expects full-year revenue to range between €18.5 billion and €19.5 billion, with an adjusted EBITDA margin (excluding non-recurring items) projected to remain between 5% and 6%. Amidst intensifying volatility in the global wind power market, Vestas has secured stable operational expectations.
From an overall industry perspective, the global wind turbine market in 2025 exhibits significant divergence. Leading companies face uneven performance driven by multiple factors including market conditions, project timelines, and strategic positioning, reflecting the complex development landscape of the global wind power sector during its transformation and adjustment phase.