According to Wood Mackenzie’s newly released Global Wind Turbine OEM Market Share 2025 report, global new wind power installed capacity reached 176 GW in 2025, surging 45% year-on-year and marking the strongest annual growth on record.
China, the United States, India and Germany remained the world’s top four core markets for new wind installations. China became the first country to exceed 100 GW of annual new installations, which strongly propelled domestic OEMs to dominate the global Top 15 ranking with nine Chinese companies on the list. Indian domestic wind turbine brands also made a successful return to the ranking.
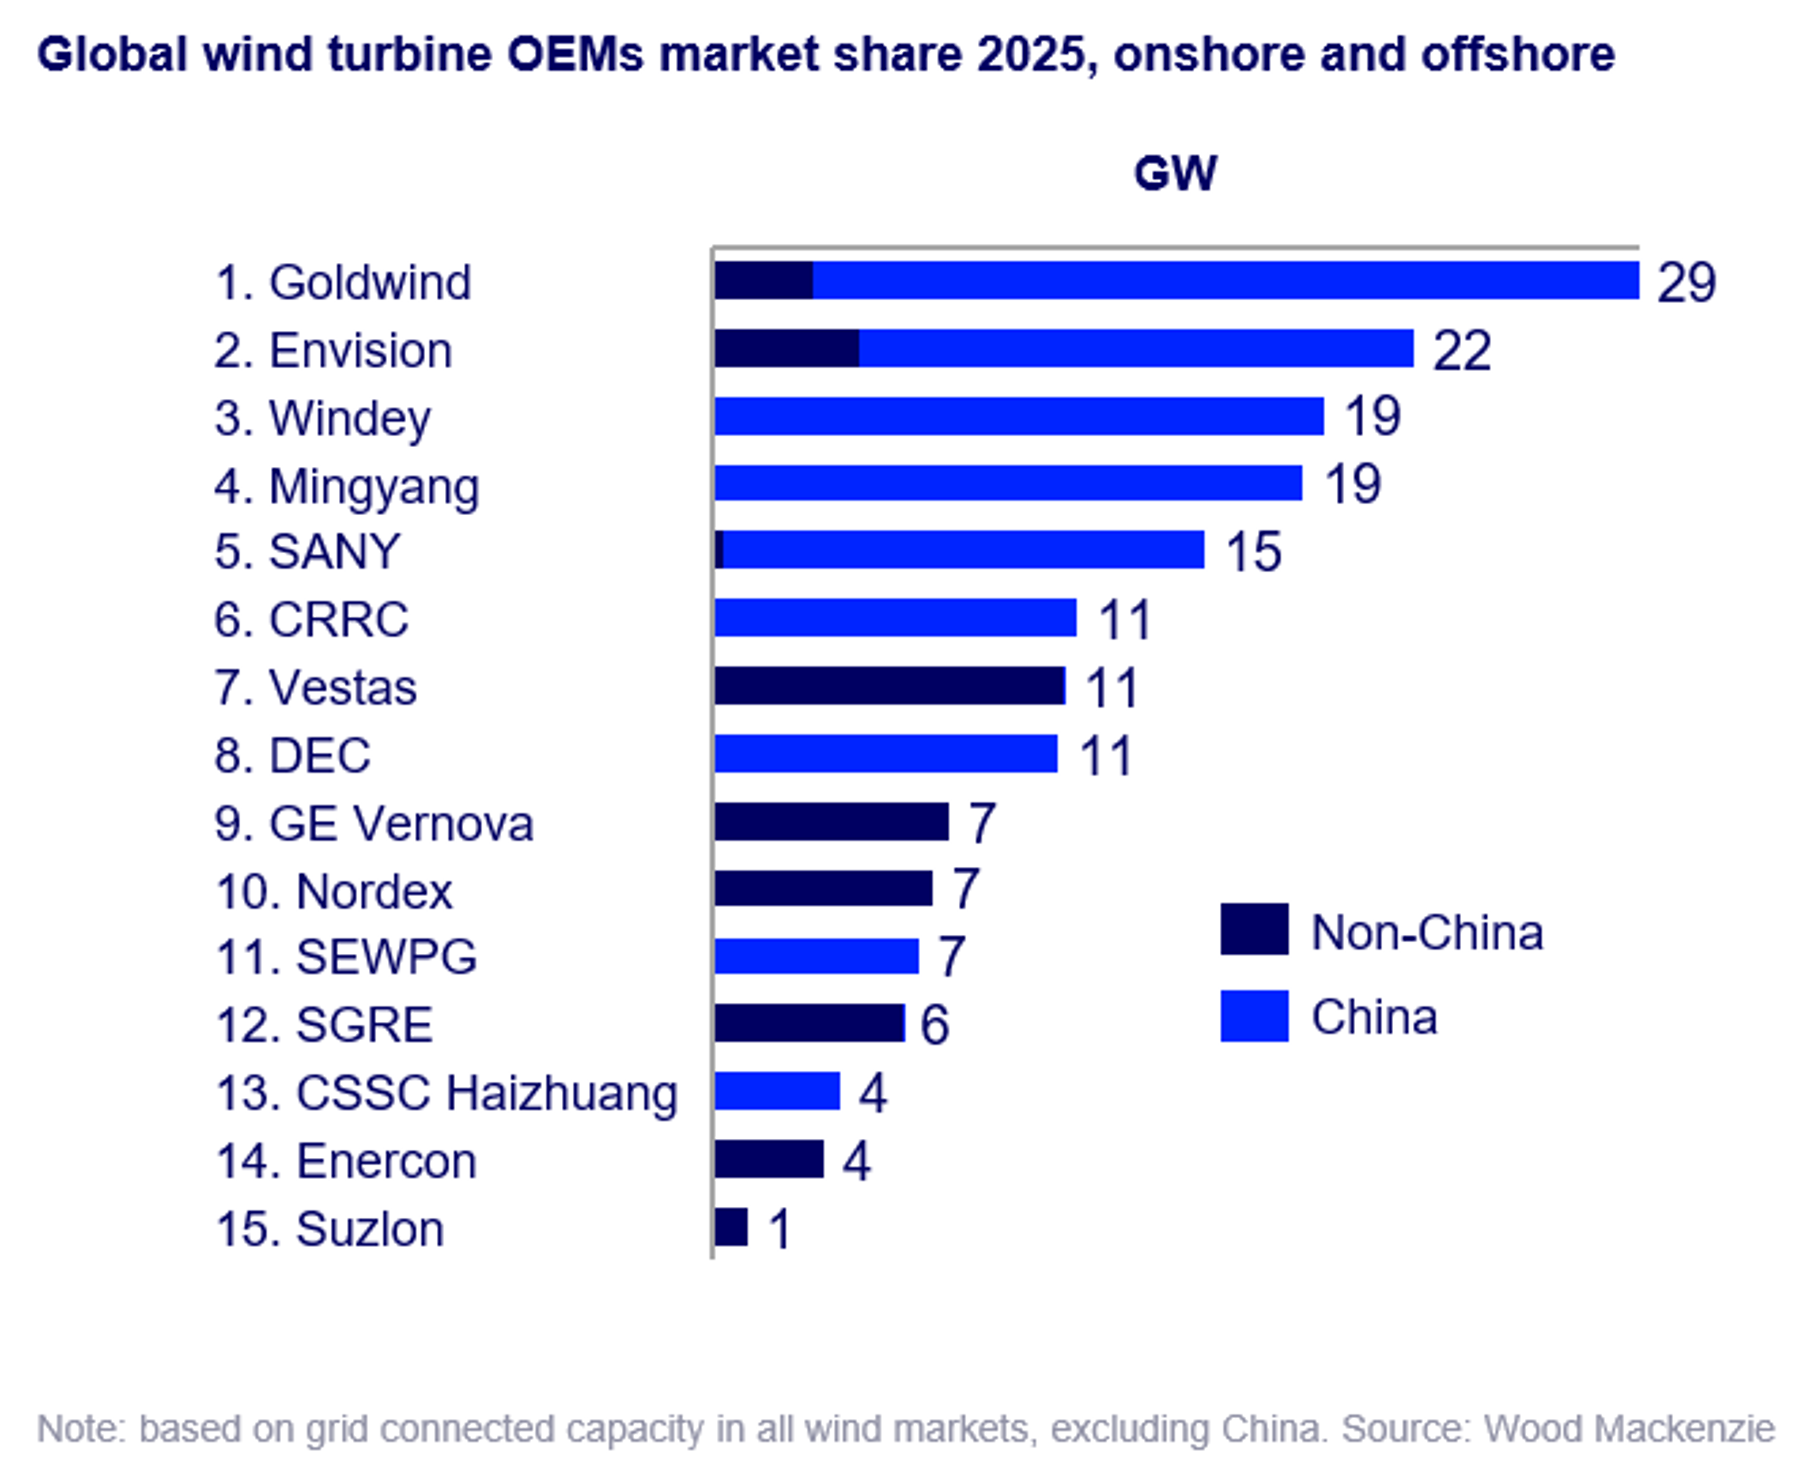
The manufacturers that have been selected into the global TOP 15 are as follows: Goldwind Technology, Envision Energy , Windey , Mingyang Intelligent, Sany, China CRRC, Vestas, DEC, GE Vernova, Nordex, SEWPG, Siemens Gamesa, CSSC Haizhuang, Enercon, Suzlon.
The year 2025 marked a historic global breakthrough for Chinese wind turbine OEMs. They took the top six spots in the global ranking and set a new record for turbine deliveries. Goldwind and Envision Energy each surpassed 20 GW of annual installations, becoming the world’s only two OEMs to cross the 20GW threshold. Meanwhile, Chinese OEMs achieved 8.5 GW of new overseas installations across 22 international markets — more than triple the 2024 volume — rapidly expanding their presence in emerging markets worldwide through cost competitiveness and fast delivery.
Despite a decline in global market share, Western manufacturers still firmly dominate the global wind power market outside of China, capturing 75% of the new installations. Vestas still maintains the most extensive market presence globally. The manufacturers from both China and the West have taken different development paths: Chinese companies focus on scale expansion and global layout, while Western companies concentrate on high-margin core markets, strictly control pricing and operational efficiency. Both strategies have achieved remarkable results by 2025.
India’s wind power market staged a robust recovery, with domestic new installations nearly doubling and local OEMs installing 2.7 GW of capacity. Suzlon successfully returned to the global Top 15 ranking. Supported by favorable policies and rising electricity demand, Indian domestic manufacturers have regained growth momentum, yet their market position faces significant challenges from the ongoing expansion of Chinese OEMs.
In terms of technology routes, China and the West have taken divergent paths but share a similar core philosophy. Chinese companies are accelerating the deployment of ultra-large onshore turbines and 16–18 MW offshore turbines, while Western manufacturers focus on the iteration and optimization of proven, mature models.